Credit Cards in Turkey: Limits, Taksit and Interest Rates
How a credit card works in Türkiye: who can get one, how the limit is set, taksit instalments, interest ceilings and fees. Try a statement example.
Table of Contents
A credit card in Türkiye lends you the bank’s money up to a limit, and a monthly statement tells you what to pay and by when. What you leave unpaid costs interest, which the central bank caps, and the state sets how many months a purchase may be spread over. The statement below runs for twelve months.
In short · checked 25.10.2026
The bank lends, the state sets the limits.
- A credit card spends the bank’s money up to a limit. You repay from a monthly statement. Pay the whole purchase debt by the due date and no interest runs on it.
- What you leave unpaid costs interest. On a lira card TCMB, the central bank, caps it at 3.25%, 3.75% or 4.25% a month, by the size of the statement debt (table valid from 01.11.2026). Banks set their own rate up to the ceiling; taxes may come on top.
- The minimum payment is a share of the statement debt: 20% on a card with a limit up to 100,000 TL, 40% above that. What stays unpaid keeps costing interest.
- Taksit, paying in instalments, has a cap by what you buy: 12 months in general, 18 for flights, travel agencies and hotels inside Türkiye, fewer for electronics or jewellery, none for food, fuel or anything spent abroad.
- For a foreigner, each bank sets its own papers. One bank’s FAQ lets a foreign national use a passport as ID and says foreign nationals apply with a guarantor. A card against a deposit also exists.
Example, not an offer · checked 25.10.2026
One card, twelve statements
Type a limit and a debt, choose how you pay each month and tap a strip to read any statement. The sheet keeps the Turkish words a bank prints; the meaning sits under each.
EKSTRE1 / 12
- Dönem borcustatement debt
- 20,000.00 TL
- Asgari ödememinimum payment
- 4,000.00 TL
- Ödenenwhat you paid
- 4,000.00 TL
- Kalan borçdebt left after paying
- 16,000.00 TL
- Akdi faizcontract interest
- 520.00 TL
- Gecikme faizilate interest
- 0.00 TL
- BSMV + KKDFtaxes on the interest
- 0.00 TL
- Yeni harcama, taksitnew spending, instalments due
- 0.00 TL
- Sonraki dönem borcudebt on the next statement
- 16,520.00 TL
ASGARİ: the minimum or more was paid. Contract interest runs on what is left.
Statement 1: the debt is 20,000.00 TL and the minimum is 4,000.00 TL (20% of it). 16,000.00 TL is left and carries 520.00 TL interest. The next statement: 16,520.00 TL.
The twelve statements as a table (example: minimum paid every month)
| Statement | Debt (TL) | Minimum paid (TL) | Interest (TL) | Debt next month (TL) |
|---|---|---|---|---|
| 1 | 20,000.00 | 4,000.00 | 520.00 | 16,520.00 |
| 2 | 16,520.00 | 3,304.00 | 429.52 | 13,645.52 |
| 3 | 13,645.52 | 2,729.10 | 354.78 | 11,271.20 |
| 4 | 11,271.20 | 2,254.24 | 293.05 | 9,310.01 |
| 5 | 9,310.01 | 1,862.00 | 242.06 | 7,690.07 |
| 6 | 7,690.07 | 1,538.01 | 199.94 | 6,352.00 |
| 7 | 6,352.00 | 1,270.40 | 165.15 | 5,246.75 |
| 8 | 5,246.75 | 1,049.35 | 136.42 | 4,333.82 |
| 9 | 4,333.82 | 866.76 | 112.68 | 3,579.74 |
| 10 | 3,579.74 | 715.95 | 93.07 | 2,956.86 |
| 11 | 2,956.86 | 591.37 | 76.88 | 2,442.37 |
| 12 | 2,442.37 | 488.47 | 63.50 | 2,017.40 |
The example: a limit of 60,000 TL, a debt of 20,000 TL, 3.25% a month (TCMB’s ceiling for a statement debt below 30,000 TL, valid from 01.11.2026), the minimum paid every month and no new spending. Example, not an offer; your bank’s rate is in your contract. TCMB sets these ceilings every month; its table shows the current ones.
Credit, bank and virtual cards: what each one spends
A credit card spends the bank’s money; a bank card spends yours. That difference decides whether you can owe anything, so it comes first.
Kredi kartı: the bank’s money, up to a limit
It lets you buy now and pay from the monthly statement. A customer the bank accepts gets it; the bank sets the limit. Pay the whole purchase debt by the due date and no interest applies; pay less and interest runs on the rest.
Banka kartı: money from your own account
It spends what is in the account it is tied to, within a daily transaction limit, so it creates no card debt and no interest. A bank may not charge an annual fee on a bank card.
Sanal kart: a number for online shopping
It is a card number with no plastic, made for online purchases. At Garanti BBVA you create it in internet banking and it is linked to a card you hold. Making and using a virtual card carries no fee, and a virtual credit card carries no annual fee.
Bankkart Jest: a credit side and a bank side
Ziraat’s page describes one card with a credit side and a bank side and two numbers on the back. You choose at the terminal or the ATM which side pays. Instalments work at contracted merchants, and cash advance works at any hour.
The logo on a card
- An international network logo, such as Visa or Mastercard, is what lets a card work abroad.
- Troy is the Turkish card network, set up in 2016 within BKM (Bankalararası Kart Merkezi, the Interbank Card Center). A Troy card works at every ATM and shop terminal in Türkiye.
- A card with only the Troy logo needs an international logo as well to work abroad.
BKM, Troy · checked 25.10.2026
Who can get a card: four checks
The bank decides, one applicant at a time. It reads your identity, your income, your credit record and, for some applicants, who stands behind you.
Identity and the foreigners’ ID number
Foreign nationals may use their passport as the identity document, says Garanti BBVA’s FAQ. The foreigners’ ID number (yabancı kimlik numarası) is the number the population registry gives to foreigners, in place of a citizen’s ID number. The loans guide explains it.
Documented income
The total limit of all a person’s cards at all banks is set from documented average income only (decision 11367 of BDDK, Türkiye’s banking regulator, 29.01.2026). Yapı Kredi counts salary and self-employment income, and regular rent, property and securities income.
Findeks, the credit score
Findeks is a credit score from the Credit Registration Bureau (KKB, Kredi Kayıt Bürosu). It summarises your repayment record: 45% repayment habits, 32% current account and debt status, 18% how much credit you use, 5% new credit. Paying after the due date is a main reason it falls.
A guarantor
Garanti BBVA’s FAQ says only people who do not work, and foreign nationals, apply with a guarantor (garantör). The guarantor’s identity card is attached, and the name, home and phone go on the form. A reference person is only phoned to check the details and does not carry the applicant’s risk.
- ApplyZiraat lists branches, mobile, the internet branch, ATMs, SMS and the call centre as ways to apply. Garanti BBVA takes a signed form with the papers at a branch.
- The bank checksIt judges the application by its credit and allocation policies and risk scores (Yapı Kredi). Garanti BBVA says it judges an application within 20 days.
- Limit and cardThe bank sets the limit, the most you may owe at one time, and issues the card.
- First useAn annual fee may be charged only after the first use that creates a debt (TCMB fee instruction).
Ask the bank first
Ask which papers it takes from a foreigner, whether a passport is enough, whether it wants a guarantor and how long the decision takes. If it asks for foreign papers to be legalised or notarised, these guides explain what that means: legalisation and notarisation.
Asking for a higher limit
- Limit requests go to the bank by branch, web, internet branch, mobile, call centre, ATM or SMS (Ziraat).
- Extra income papers can raise a limit: Garanti BBVA lists a title deed, a rent contract, a car registration and another bank’s account book.
Four banks’ own pages: one dated fact each
Each card holds one fact from a bank’s own page, checked on the date shown. The cards run in alphabetical order and are not a ranking.
How to read the cards
- One fact per bank, from its own page and with its date.
- Alphabetical order. No bank is placed above another.
 Cash-advance page
DenizBank
A cash advance (nakit avans) is cash drawn on the card. Interest on it generally starts the same day, and the cash-advance limit is only part of the card limit. An instalment cash advance exists, possibly with another rate or fee.
 Card FAQ
Garanti BBVA
Spending abroad is converted to USD at the card network’s rate, then to lira at the bank’s rate, with up to 3% commission added. A foreign-currency statement must be paid in full. See also exchange rates.
Yapı Kredi
It judges applications by its credit and allocation policies and risk scores. For income it counts salary and self-employment income, and regular rent, property and securities income.
 Card FAQ
Ziraat
A limit change can be asked for at a branch, on the web, at an ATM, by SMS, by phone or in the app. The card debt can be paid in Ziraat Mobil, Bankkart Mobil, the internet branch, the call centre, an ATM, by automatic instruction or by EFT. More on the bank: Ziraat Bank guide.
The limit: what sets the most you can owe
The limit is the most you may owe on the card at one time. The bank sets it, inside a cap the state sets for all your cards together.
- What it is
- The most you can owe on the card at one time. What you spend or draw uses it up until you pay it back.
- Who sets it
- The bank. The state rule is that the total limit of all a person’s cards at all banks is set from documented average income only, and the bank reports that income to the Risk Centre of the Banks Association of Türkiye (TBB) on the day it sets the limit. BDDK decision 11367, 29.01.2026
- How much
- Garanti BBVA words it this way: all your cards together up to 2 times your average monthly net income in the first year, up to 4 times later. A high limit at another bank can stop a rise. Its card FAQ, checked 25.10.2026
- When it changes
- You can ask for a rise with extra income papers. Banks must bring every limit within the cap by 01.01.2027.
- Why it matters
- The limit also sets the minimum payment: 20% of the statement debt up to a limit of 100,000 TL, 40% above. BDDK decision 11581, 01.10.2026
Example, not an offer · checked 25.10.2026
Your income and a card limit
Type a monthly income. The gauge shows what the 2× and 4× rule from Garanti BBVA’s card FAQ gives for all your cards together, and the limit where the minimum payment share changes.
| Monthly net income | Year one (2 ×) | Later years (4 ×) | Minimum payment at that limit |
|---|---|---|---|
| 15,000 TL | 30,000 TL | 60,000 TL | 20% in year one, 20% later |
| 30,000 TL | 60,000 TL | 120,000 TL | 20% in year one, 40% later |
| 60,000 TL | 120,000 TL | 240,000 TL | 40% in year one, 40% later |
Taksit: paying a purchase in instalments
Taksit splits the price of a purchase into monthly parts that land on your next statements. The state caps the months by what you buy: 12 in general, 18 for travel inside Türkiye, fewer for some goods, none for others.
BDDK instalment table · checked 25.10.2026
How many months, by what you buy
Each shutter is raised as high as the most months the state allows for that kind of purchase. A shut shutter means no instalments at all. Tap one to read the rule.
- 18monthsDomestic airline, agency, hotel
Airline, travel agency and hotel spending inside Türkiye can be spread over up to 18 months.
- 12monthsThe general rule, refurbished phones
The general ceiling is 12 months, for purchases and for cash withdrawals. A refurbished phone bought from a refurbishment centre or an authorised seller also gets 12 months, with no price limit.
- 9monthsFurniture, appliances, health, TV up to 5,000 TL
Furniture, electrical appliances and health products: 9 months. A TV priced up to 5,000 TL: 9 months.
- 6monthsTablets, clubs, associations
Tablets, and payments to clubs and associations: 6 months.
- 4monthsElectronics
Electronics: 4 months, including a TV of 5,000 TL or more.
- 3monthsJewellery, Northern Cyprus travel
Jewellery other than minted gold (basılı, such as gold coins) and gold bars (külçe): 3 months. Northern Cyprus airline, travel agency and hotel spending: 3 months.
- No taksitMinted gold, gold bars, telecoms, direct marketing
No instalments on minted gold (basılı, such as gold coins) or gold bars (külçe), on telecommunications, or on direct marketing.
- No taksitAnything spent abroad
No instalments on anything spent abroad, nor on airline, travel agency and hotel spending abroad. Northern Cyprus is the exception (3 months).
- No taksitFood, fuel, cosmetics, office supplies, gift cards
No instalments on meals and food, fuel, cosmetics and office supplies, nor on gift cards, gift cheques and similar products that include no concrete good or service.
These are ceilings: a bank may offer fewer months. Corporate cards may spread purchases and cash withdrawals over up to 18 months.
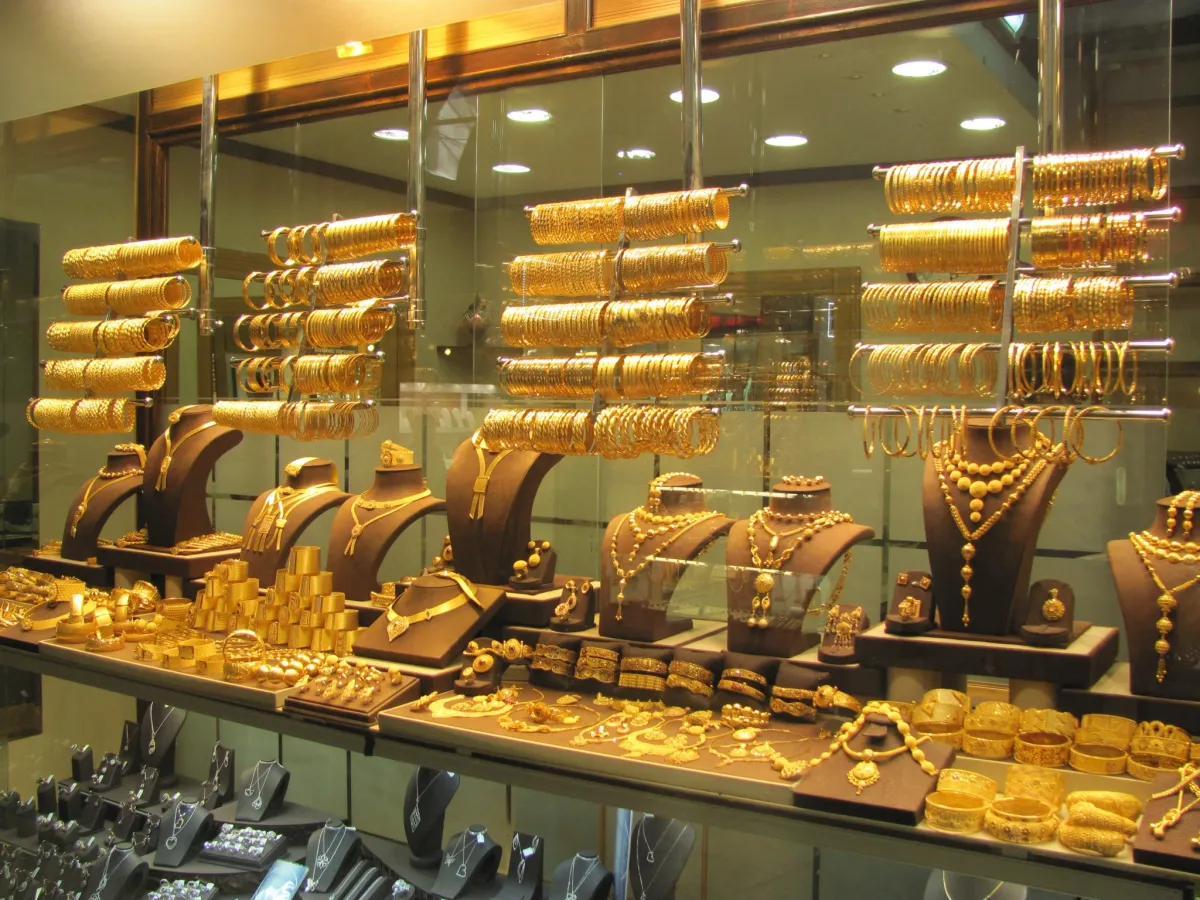
Jewellery and gold have the shortest rules
- 3 months for jewellery other than minted gold (basılı, such as gold coins) and gold bars (külçe).
- No instalments for minted gold or gold bars.
- Each instalment is added to that month’s statement debt in the tool above.
BDDK instalment table · checked 25.10.2026
- What it is
- The price is split into monthly parts. Each part is added to a statement, so the debt on that statement includes it.
- Cash
- The general ceiling of 12 months covers cash withdrawals too. DenizBank says an instalment cash advance may carry another rate or fee.
- Abroad
- No instalments on anything spent abroad.
- A bigger sum
- A bank loan is another product with its own rules: see Loans in Turkey.
The monthly cycle: statement, due date, minimum
Every month the bank adds up what you spent and posts a statement. Five terms run the cycle: the statement, the cut-off date, the due date, the statement debt and the minimum payment.
From the shop to the statement
- You pay by card in a shop. The purchase joins the debt of the period.
- The cut-off date closes the period. The bank adds up the spending.
- The statement follows. You pay by the due date.
Which term?
- What it is
- The statement (ekstre, also hesap özeti) is the document the bank sends after each cut-off date. It lists the spending, limit, debt and payments between the last cut-off date and this one.
- Why
- It is where you read what you owe and by when you pay.
- Who
- The bank issues it. Garanti BBVA posts it the day after the cut-off date and can also send it by e-mail or SMS.
- How much
- It shows the statement debt and the minimum payment. A bank may not charge for sending it (TCMB fee instruction, 13.01.2026).
- What it is
- The cut-off date (hesap kesim tarihi) is the day each month on which the bank closes the period and adds up what you spent.
- Example
- Garanti BBVA’s example: with a cut-off date on the 3rd, spending from 3 March to 3 April is one period debt.
- Who
- The bank sets it. Garanti BBVA lets you change it once in a calendar year by calling the bank.
- Why it matters
- Interest on the unpaid part runs from the cut-off date (Garanti BBVA).
- What it is
- The due date (son ödeme tarihi) is the last day to pay the statement.
- Until when
- Garanti BBVA: at a branch until 17:00 on the due date; by mobile app, call centre or internet banking until 00:00.
- Channels
- Garanti BBVA lists its app, call centre, internet banking, ATMs, branches, automatic payment, EFT from other banks, online PTT branches and payment points.
- Fees
- Payment points and PTT online branches: 19.17 TL, charged in the next statement period; payment points up to 20,000 TL a month (Garanti BBVA). Paying through the issuer’s own channels carries no fee (TCMB).
- Automatic payment
- The balance must be in the account by the morning of the due date (Garanti BBVA).
- What it is
- The statement debt (dönem borcu) is what you owe for the period on the statement.
- Why it matters
- The minimum payment is a share of it, and TCMB’s interest ceiling depends on its size.
- Pay it all
- Pay the whole purchase debt on the due date and no interest applies (Garanti BBVA). A cash advance carries daily interest.
- Abroad
- A statement in foreign currency must be paid in full (Garanti BBVA).
- What it is
- The minimum payment (asgari ödeme) is the smallest amount to pay by the due date.
- How much
- 20% of the statement debt on a card with a limit up to 100,000 TL; 40% above. BDDK decision 11581, 01.10.2026
- If you pay it
- Pay the minimum or more and contract interest (akdi faiz) applies to what is left (Garanti BBVA).
- If you pay less
- Late interest (gecikme faizi) runs on the unpaid part of the minimum. At Ziraat a card with a missed or short minimum is closed to cash advance; missed twice in a row, it is closed to shopping too; paying the minimum restores normal status.
- Findeks
- Paying after the due date is a main reason the score falls (KKB).
Minimum payment · BDDK decision 11581, 01.10.2026
20% of the debt, 40% above a 100,000 TL limit.
The same debt of 20,000 TL, the minimum paid every month, 3.25% a month, no new spending and both taxes left at 0. On a limit of 60,000 TL the minimum is 20%: after 12 statements 2,687.05 TL of interest has been charged and 2,017.40 TL is still owed. On a limit of 120,000 TL the minimum is 40%: 1,021.70 TL of interest and 63.91 TL still owed.
Each minimum is a share of what is left, so the debt shrinks slowly. Example, not an offer; your bank’s rate is in your contract.
Interest: who sets the ceiling
A card charges nothing on purchases you repay in full by the due date. On the rest it charges interest, and TCMB caps the monthly rate.
TCMB ceilings · valid from 01.11.2026
3.25%, 3.75% or 4.25% a month at most.
The ceiling for contract interest on a lira card depends on the statement debt: below 30,000 TL, 3.25%; from 30,000 to 180,000 TL, 3.75%; above 180,000 TL, 4.25%, which also applies to corporate cards. The table valid from 01.10.2026 is the same.
Banks set their rate freely up to the ceiling. TCMB sets these ceilings every month; its table shows the current ones.
| Kind of debt | Contract interest, at most a month | Late interest, at most a month |
|---|---|---|
| Lira card, statement debt below 30,000 TL | 3.25% | 3.55% |
| Lira card, statement debt 30,000 to 180,000 TL | 3.75% | 4.05% |
| Lira card, statement debt above 180,000 TL, and corporate cards | 4.25% | 4.55% |
| Cash withdrawal or use, also overdraft accounts | 4.25% | 4.55% |
| Foreign-currency card debt | 2.98% | 3.28% |
TCMB table, valid from 01.11.2026 · checked 25.10.2026 · TCMB: maximum interest rates on card transactions.
Who sets the ceiling
- TCMB (Türkiye Cumhuriyet Merkez Bankası, the central bank) works the ceilings out by a set method and posts the table on the fifth-last working day of each month.
- Your bank may charge less. The rate in your contract is the one that counts.
Which interest?
- What it is
- Contract interest (akdi faiz) is the price of the unpaid part of your statement debt, quoted as a rate a month.
- Who pays
- You, when you pay the minimum or more but not the whole debt.
- How much
- Up to the ceiling above. Your contract states your bank’s rate.
- When
- On the rest, until the next payment date or, with no payment, the next cut-off date (Garanti BBVA).
- What it is
- Late interest (gecikme faizi) is the monthly rate on the unpaid part of the minimum payment, when you pay less than the minimum.
- How much
- Ceilings of 3.55%, 4.05% and 4.55% a month on the same three debt sizes.
- Over the limit
- Garanti BBVA also names an over-limit interest (limit aşım faizi), charged when spending and cash withdrawals pass the card limit.
- What it is
- A cash advance (nakit avans) is cash drawn on the card limit.
- When interest starts
- DenizBank: generally the same day. Garanti BBVA: daily interest.
- How much
- The ceiling is 4.25% contract and 4.55% late a month, whatever the statement debt. The fee is at most 1% of the advance, and none for an instalment cash advance (TCMB fee instruction).
- Limit
- The cash-advance limit is only part of the card limit (DenizBank).
- Conversion
- Spending abroad is converted to USD at the card network’s rate, then to lira at the bank’s rate, with up to 3% commission added (Garanti BBVA).
- Statement
- A foreign-currency statement must be paid in full; the minimum on a lira statement varies with the limit (Garanti BBVA).
- Ceiling
- TCMB: 2.98% contract and 3.28% late a month on foreign-currency card debt.
- Instalments
- None on anything spent abroad.
Two taxes: ask the bank
BSMV (Banka ve Sigorta Muameleleri Vergisi) is a tax on banking and insurance transactions; KKDF (Kaynak Kullanımı Destekleme Fonu) is a levy banks collect on some loans. On a bank loan both are 15% of the interest, as Loans in Turkey shows. Which taxes apply to card interest, and at what rate, is for your bank to say. The statement above starts both at 0: type what your bank states.
Fees and your rights: what a bank may charge
A fee is separate from interest. TCMB’s fee instruction of 13.01.2026 says what a card may be charged for and what must stay free.
A fee-free card must be on offer
A bank must offer a card type with no annual fee, judged by the same limit rules as a fee card. A holder of a fee card may switch to it at the same limit. The fee may be charged only after the first use that creates a debt.
No fee while the card sits unused
A card with no movement for 180 days in a row carries no annual fee. Unpaid idle fees are held for 12 months at most, then cancelled, with no interest on them.
A balance is no reason to refuse
A bank cannot refuse to cancel a card because a debt is outstanding. A card cancelled that way carries no annual fee in the repayment period.
Several services stay free
Statement delivery, making and using a virtual card, up to two replacement cards a year after a loss or theft (at cost after two), paying the card debt through the issuer’s own channels, and postponing, splitting or adding instalments to a balance or extending the due date.
At most half the main fee
The annual fee of an additional card is at most 50% of the main card’s. Garanti BBVA: free in year one, then half the fee; the limit is shared with the main card.
At most 1% of the advance
The fee for a cash advance is at most 1% of the amount; there is none for an instalment cash advance. At another bank’s ATM an extra ATM fee can apply.
- The issuer firstA dispute about a card fee goes first to the bank that issued the card.
- A small amount: the arbitration committeeIf the bank does not settle it and the amount is below a money limit set under the consumer law, the consumer arbitration committee (Tüketici Hakem Heyeti, a board that decides consumer disputes) takes it up.
- A larger amount: mediation, then the courtAbove that limit the dispute goes to a consumer court. Before the case you must first apply to mediation (arabuluculuk: a meeting with a neutral mediator to reach an agreement); the law makes it a condition of the case.
Steps as the Ministry of Trade’s statement of 21.11.2020 gives them · checked 25.10.2026 · Ministry of Trade statement.
A card against a deposit: what two banks say
A secured card is a card issued against collateral you leave at the bank. The bank decides who gets one and on what terms.
Garanti BBVAAnahtar Kart
The program starts at a collateral of 700 TL kept in your account. The amount is blocked and the card application is approved against it. Payments are reviewed every 6 months, and if the bank finds them suitable the block is lifted and you use the card without collateral.
Teminatlı Kredi Kartı
A card against a fixed collateral. The bank’s tips page says it can improve the chances of approval and raises the credit score.
- CollateralYou place money at the bank and it is blocked. At Garanti BBVA the program starts at 700 TL.
- The cardThe bank issues a card and sets its limit against the collateral.
- A reviewGaranti BBVA looks at the payments every 6 months.
- The blockIf the payments were suitable, the block is lifted.
Ask the bank first
Ask what limit the collateral buys, whether the blocked money earns anything, and what happens to it if a card debt stays unpaid. A secured card has a statement, a minimum payment and a due date like any other.
Sources and limits
Show the pages checked
- BDDK decision 11581, 01.10.2026: minimum payment on credit cards — BDDK, checked 25.10.2026
- BDDK decision 11367, 29.01.2026: total limit of a person’s cards — BDDK, checked 25.10.2026
- Kredi Kartı Taksit Sınırları ve Yasakları (instalment table, last footnote 24.08.2023) — BDDK, checked 25.10.2026
- Banka Kartları ve Kredi Kartları Kanununa İlişkin Düzenlemeler (list of the law, regulation and tables) — BDDK, checked 25.10.2026
- Kredi Kartı İşlemlerinde Uygulanacak Azami Faiz Oranları (table valid from 01.11.2026) — TCMB, checked 25.10.2026
- Finansal Tüketicilerden Alınacak Ücretlere İlişkin Tebliğe (2020/7) İlişkin Uygulama Talimatı, 13.01.2026 — TCMB, checked 25.10.2026
- Kredi Kartı Aidatlarının İadesine İlişkin Basın Açıklaması, 21.11.2020 — Ministry of Trade, checked 25.10.2026
- Troy — BKM (Interbank Card Center), checked 25.10.2026
- Findeks Kredi Notu — Credit Registration Bureau (KKB), checked 25.10.2026
- Yabancılar ve Uluslararası Koruma Kanunu (Law 6458) — Mevzuat Bilgi Sistemi, checked 23.10.2026
- Kredi kartları: sıkça sorulan sorular — Garanti BBVA, checked 25.10.2026
- Kartlar: sıkça sorulan sorular — Ziraat Bankası, checked 25.10.2026
- Bankkart — Ziraat Bankası, checked 25.10.2026
- Nakit avans — DenizBank, checked 25.10.2026
- Kredi kartı ipuçları — Yapı Kredi, checked 25.10.2026
The cover is an illustration. Photos are from Wikimedia Commons, with their authors, dates and file pages in the captions; the 1940s picture comes from the Turkey in Photographs archive, shared with no known copyright restrictions. The three logos are unaltered SVG files from Wikimedia Commons (public domain, trademarked); each is linked to its file page on its card, and a logo only names the bank, it does not mean the bank took part in this guide.
This guide is general information, not financial advice. It does not recommend a bank or a card. Ask your bank for its current terms, and read the contract before you sign.