Loans in Turkey: Payments, Costs and Foreign-Customer Requirements
Table of Contents
Money in Turkey · Practical borrowing guide
A manageable monthly payment can still hide an expensive loan. Before borrowing in Turkey, put the repayment schedule, extra costs and application requirements next to each other. That is especially important if your income, residence status or documents come from another country.
This guide explains consumer loans, mortgages, car loans and participation-bank financing. Use the calculator to explore a fixed-rate payment plan, then compare it with a written quote from the lender. All example rates are invented for illustration; none is a current bank offer or a promise of approval.
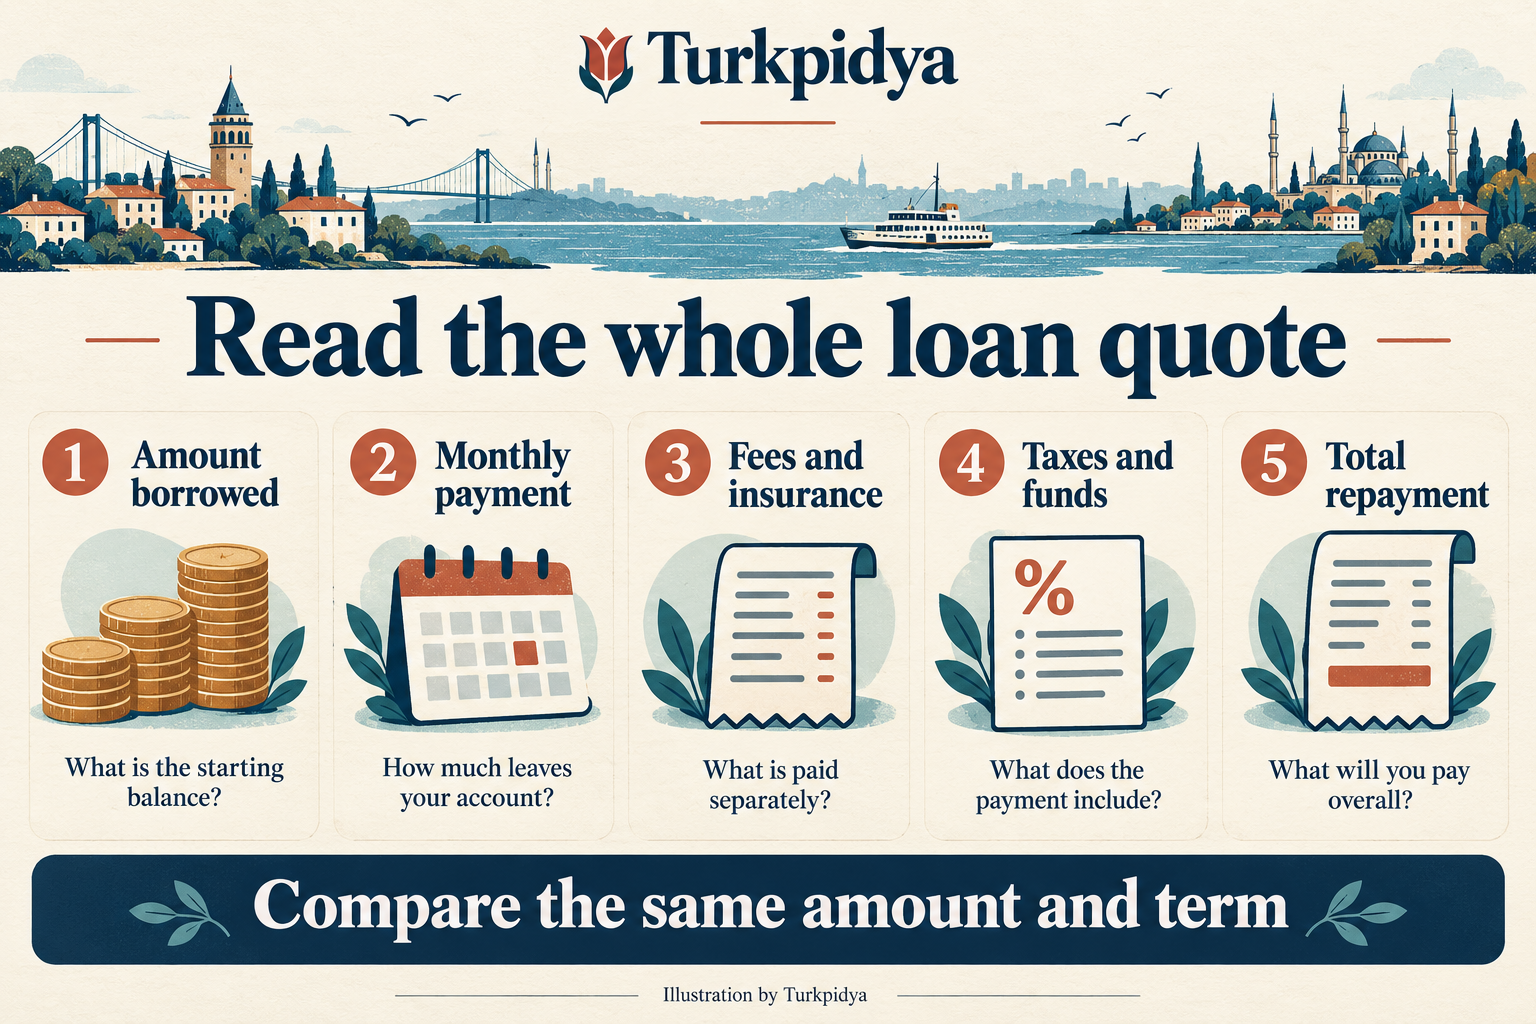
How much money will I receive? What will leave my account each month? What will I pay in total, including costs paid outside the instalments?
Which kind of loan do you need?
Consumer loan
İhtiyaç kredisi is personal borrowing for general needs. Ask for the permitted term for your amount and whether the quote assumes salary payments, insurance or another condition. An account with a bank does not itself establish loan eligibility.
Mortgage
Konut kredisi finances a home, with the property used as security. The bank’s valuation can differ from the price you agree with the seller. Budget for that gap as well as appraisal, mortgage-establishment and other purchase costs.
Car loan
Taşıt kredisi is tied to a vehicle. The vehicle’s value, age and type can affect the financed amount and term. Compare a dealer’s financing package with its cash price, and separate the loan from insurance and running costs.
Participation financing
Participation banks use financing contracts with a profit amount rather than conventional loan interest. “Interest-free” does not mean cost-free: compare the complete payment schedule, fees and total paid. The lender’s contract determines how its financing works.
Consumer-loan term limits
The banking regulator’s general consumer-loan term limits, announced on 14 February 2025, use these amount bands. A bank may offer less than the maximum. Separate rules apply to mortgages, vehicle loans and other specific products; the calculator’s 360-month range is not an eligibility rule.
| Loan principal | Maximum term |
|---|---|
| Up to and including 125,000 TRY | 36 months |
| Over 125,000, up to and including 250,000 TRY | 24 months |
| Over 250,000 TRY | 12 months |
See where each payment goes
The starting balance is the principal. Each payment repays part of it and covers that month’s interest and any modelled charges. Interest falls as the balance falls, so the principal share usually grows through the schedule.
Loan repayment calculator
Enter a fixed monthly interest rate and the lender’s tax/fund percentages, if applicable. These are percentages of interest, not of the loan amount. Enter 0 explicitly for an excluded or non-applicable item.
Regular monthly payment
Total scheduled interest
Tax and fund charges
Total instalments
Entered upfront costs
Instalments plus upfront costs
Adjusted final payment
Annual-equivalent interest only
Repayment composition: navy = principal; terracotta = interest; teal = tax and fund; gold = upfront costs. The amounts above provide the same information in text.
Fixed interest, equal monthly periods, payments at each month’s end, and no payment holiday. Each month’s interest is rounded to kuruş; each entered tax and fund charge is then calculated on that rounded interest. The regular instalment uses the combined rate; the final payment clears the remaining balance. A bank’s day-count and rounding rules can differ.
Upfront costs are added separately and do not earn interest here. If a charge is financed into the balance, include it in the amount borrowed and do not add it again as an upfront cost. Recurring insurance, future rate changes, late charges and unknown fees are excluded. A zero entry excludes that charge; it does not establish a tax exemption.
For the payment formula, let P be the principal, n the number of months, and q the monthly interest rate multiplied by (1 + tax fraction + fund fraction). The unrounded payment is P × q ÷ [1 − (1 + q)−n]. At zero interest, divide P by n instead. Monthly rounding can change the final instalment.
The annual-equivalent figure is (1 + monthly interest rate)12 − 1. It excludes fees and tax/fund charges and is not the legally disclosed annual total cost. This is a planning illustration, not a quote or personal financial advice.
Your illustrative repayment schedule
Scroll the table sideways if needed. Each row splits the payment into principal, interest and entered charges.
| Month | Payment | Principal repaid | Interest | Tax | Fund | Balance |
|---|
Why a smaller payment can cost more overall
Here is the same 100,000 TRY loan at an invented 3% monthly rate, with 500 TRY paid upfront and taxes, funds and insurance excluded. Extending the term reduces the monthly payment but leaves money outstanding for longer.
| Term | Regular payment | Interest | Instalments + upfront cost |
|---|---|---|---|
| 12 months | 10,046.21 TRY | 20,554.50 TRY | 121,054.50 TRY |
| 24 months | 5,904.74 TRY | 41,713.82 TRY | 142,213.82 TRY |
The final payments are adjusted to 10,046.19 TRY and 5,904.80 TRY respectively. The bars compare interest amounts, starting from zero. These are arithmetic scenarios, not available products.
Read the whole loan quote
A monthly rate is not an annual borrowing cost. In the example, 3% × 12 is 36%, while compounding the same monthly rate mathematically gives about 42.58%. Neither number is a substitute for the lender’s disclosed annual total cost. The central bank’s policy rate is also a different measure from a retail quote.
The Ministry of Trade’s consumer-credit guidance caps the allocation fee at 0.5% of principal. It also says credit-related insurance requires an express request, an uninsured offer must be available, and suitable cover from another insurer must be accepted. That does not make every property-related insurance obligation optional.
For consumer credit, the same guidance describes a 14-day withdrawal right; if the money has been used, principal and accrued interest must be repaid within 30 days of the withdrawal notice. Early payment brings a reduction in the relevant interest and costs. Ask the lender for the settlement amount and any insurance refund in writing. Mortgage contracts have their own rules, so do not copy consumer-loan cancellation or early-payment assumptions into a home purchase.
Can a foreign customer borrow in Turkey?
Some banks publish products for foreign customers, but eligibility is assessed for the applicant and product. Nationality, residence, income evidence, existing debts, credit history and the proposed security can matter. A general product page is not an approval.
There is no single document checklist or deposit percentage that applies to every foreign borrower. In particular, do not assume that all banks demand 12–24 months left on a residence permit, always require a Turkish guarantor or universally lend only 50% of a home’s value. Ask the bank to confirm its current policy before paying for translations or making a non-refundable commitment.
İşbank: a stated residence requirement
İşbank’s housing page for foreign residents describes a foreign-customer route, separate from its expatriate product for Blue Card holders or dual citizens. Its loan application checklist lists a passport, income evidence, application form and valid residence permit for the applicant and guarantor. For a mortgage, it adds the seller’s title deed and land-office evidence of restrictions on the property. Ask whether a guarantor is needed in your case and what document format the branch will accept.
Kuveyt Türk: check the exact product
Kuveyt Türk’s expatriate property financing is aimed at Turkish citizens earning foreign-currency wages abroad and also names eligible foreign nationals on its stated country list. The page advertises financing up to 50% of appraised value for this product. That is a product-specific statement, not a nationwide foreigner limit. Ask the branch to confirm nationality eligibility, residence and income documents, the offered currency and the property’s eligibility. The page requires residential title and an occupancy permit and excludes buildings awaiting demolition.
Garanti BBVA: useful general requirements
Garanti BBVA’s mortgage guidance names identity information, title deed and income evidence, with additional documents when needed. It describes a first mortgage over the purchased property. This general checklist does not resolve every foreign applicant’s requirements; ask for a foreign-customer checklist, accepted overseas income and the available currency for your situation.
Ziraat and DenizBank: do not infer eligibility
Ziraat’s required-document list includes an application, identity document or passport, evidence of income and additional branch requests. Its mortgage list adds the property’s title deed and extra evidence for business owners. A passport appearing on a list does not guarantee that a particular foreign applicant or overseas income will qualify.
DenizBank’s standard mortgage page lists address, income and property documents, while its public eligibility answer refers to Turkish citizens. Foreign readers should therefore obtain confirmation of a suitable product directly, rather than relying on a general “foreigner-friendly” label.
Build the application file in the right order
- Confirm the product first. Tell the bank your nationality, where you live, where your income comes from and what you want to finance. Ask whether the branch handles that combination.
- Request its written document list. Check passport or identity requirements, residence and address evidence, tax-number details, income records and any guarantor or credit-report requirements. Ask which documents must be current.
- Check overseas-document formalities. Ask which language, translation, notarisation or legalisation the bank requires. Our guides to using foreign documents in Turkey and notarisation in Turkey explain the separate steps; confirm the bank’s list before paying for them.
- Add the purchase paperwork. For property, check title, restrictions, occupancy status and appraisal. For a vehicle, ask which invoice, registration and valuation documents apply. Keep the seller’s price separate from the value the bank accepts.
- Get a complete written quote. Ask for the net amount released, instalments, total cost, applicable taxes, fees, insurance and early-payment terms. Compare the same principal and term, with and without optional items.
- Review before committing. Understand what is refundable if the application or purchase does not proceed. Use independent professional advice when the contract, language or property position is unclear.
A mortgage deposit is more than one percentage
The central bank’s May 2026 financial-stability report describes the January 2026 housing-loan changes: limits vary with appraised value and energy class, and the old new-versus-second-hand distinction was removed. Your bank’s product can be more restrictive than the regulatory maximum.
For a purely hypothetical purchase price of 4 million TRY and an approved loan of 2 million TRY, the purchase-price gap alone is 2 million TRY. Appraisal, transfer-related costs, insurance, legal assistance and any other payable charges still need their own budget. Do not calculate the deposit from an advertised percentage until you know what value that percentage applies to.
What about a developer’s payment plan?
A developer may offer instalments, but “0% interest” alone does not show whether a plan is cheaper. Compare its total selling price with the cash price, deposit, instalments and any large final payment. Check indexation, delivery dates, title transfer, security for payments and what happens if construction is delayed or you cannot continue. A private payment plan is not automatically safer or better than a bank mortgage.
Keep currency risk and other borrowing separate
If your income and repayments use different currencies, exchange-rate changes can alter the effort needed to meet a payment. In a simple illustration, a fixed 1,000-unit foreign-currency payment costs 20% more in lira if the lira price of that currency rises 20%. This is a sensitivity example, not an exchange-rate forecast. Inflation does not automatically make debt affordable: your income and essential costs may change at different speeds.
Credit-card cash advances and overdrafts are not interchangeable with the fixed monthly model above. Their dates and charging structure can differ. For a car purchase, include vehicle insurance costs and the practical steps for buying a car in Turkey as a foreigner. If money is arriving from abroad, use Turkpidya’s lira currency converter for an indicative comparison, then check the provider’s actual conversion rate and transfer fees separately from the loan.
Keep the bank’s written offer, pre-contract information and repayment schedule together. If a number in the offer differs from this calculator, ask the bank to explain the difference before relying on either figure.